Instant payouts vs. push-to-card: which is faster and cheaper?
Payments
November 16, 2026
|
Aeropay Team
This article was written by the payments nerds at Aeropay. Our goal is to provide you with solid insights to help your business operationalize more efficient, value-focused payments.
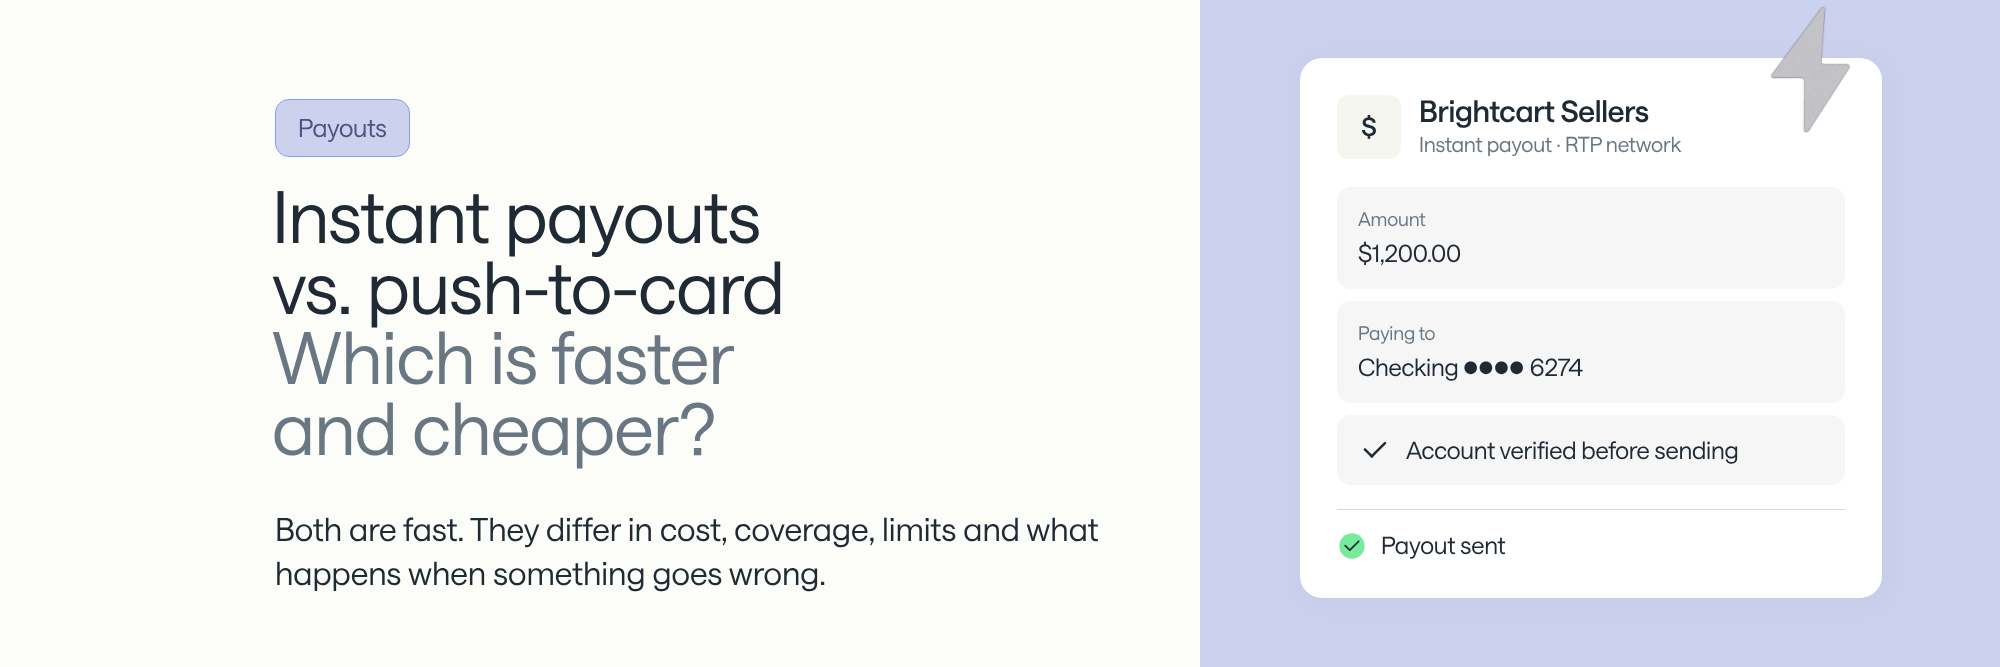
Customers, sellers and gig workers expect their money in minutes, not days. US businesses have two fast ways to deliver it. Push-to-card sends money to a debit card over the card networks, and instant bank payouts send it to a bank account over real-time payment rails.
Instant bank payouts over the RTP network or FedNow land in a recipient's bank account in seconds, any day of the year, usually for a flat fee per payout. Push-to-card reaches a debit card about as fast, but it is usually priced as a percentage, so it costs more as payouts grow. Make bank payouts the default.
All four options move money to US recipients. They differ in where the money lands, how they're priced and what you need to collect from the recipient.
Limits depend on the rail. The Clearing House raised the RTP network's limit to $10 million per payment, effective February 9, 2025. Federal Reserve Financial Services raised the FedNow network limit to $10 million in November 2025. Banks on both networks set lower limits based on their own risk policies. Same Day ACH payments can be up to $1 million each under the Nacha Operating Rules, a limit Nacha raised from $100,000 on March 18, 2022.
A percentage fee grows with every dollar of the payout, while a flat fee stays the same. Push-to-card is usually priced the first way and instant bank payouts the second, so the gap between them widens as payouts get larger. Doubling a payout doubles a percentage fee and leaves a flat fee unchanged.
That makes your typical payout size the deciding factor. On a small reward or rebate, the two fees land close together depending on the rates you're quoted, and the convenience of a card wins. On a sportsbook withdrawal, a trader's profit split or a weekly gig worker payout, the percentage fee keeps climbing while the bank payout costs the same. Compare quotes at your median payout and your largest common payout, not your smallest, and ask whether the card option carries a minimum fee.
Push-to-card requires the recipient's debit card number, and handling card numbers brings your payout flow under the PCI Data Security Standard, which applies to any business that stores, processes or transmits cardholder data. Using a provider's hosted card fields or tokens shrinks that scope, but it is still a card program to manage.
The card also has to qualify. Push payments reach only debit cards whose issuer accepts them, so some recipients will find their card declined at withdrawal.
A bank payout needs a bank account and routing number instead. Payments over RTP and FedNow are final once sent, so the account should be confirmed as open and owned by the person you're paying before any money moves. We explain which rails can be reversed in What are A2A payments, and are they safe?
Automatic fallback is what makes a bank-first approach work, because some banks that advertise real-time payments still fail to receive them in practice. Aeropay routes payouts over RTP or FedNow first and falls back to ACH when the recipient's bank can't receive a real-time payment, so not every payout is instant. Aeropay Payouts uses the same integration merchants already use to accept pay by bank, and Aeropay can check a recipient's real-time balance and verify account ownership before releasing large payouts. Trading platform Topstep cut trader payout times from 3 days to 9 seconds with Aeropay instant payouts.
For how much speed your recipients expect, see How fast is fast enough for payouts? For what to ask a payout provider, see How should US marketplaces pay sellers instantly? For running deposits and payouts on one integration, see What does a bank payment API need to handle both pay-ins and payouts?
No. Push-to-card sends money over the Visa or Mastercard networks to the account behind a debit card. An instant bank payout sends money over the RTP network or FedNow straight to a bank account, using its account and routing numbers. Both arrive quickly, but they run on different rails with different pricing.
Yes, if they go over the RTP network or FedNow. FedNow and the RTP network both settle payments 24 hours a day, 365 days a year, including weekends and holidays. Same Day ACH and standard ACH settle only on business days, so a payout that falls back to ACH on a Saturday arrives the next business day.
The payout goes by ACH instead, as long as your provider falls back automatically. If it's sent before the day's last Same Day ACH processing window, it settles that business day. If it's sent after that window, it settles the next business day. Check which fallback your provider uses before you promise recipients a time.
Yes, when your recipients are split. Offer bank payouts as the default and push-to-card as the alternative for recipients who won't link a bank or whose bank can't receive real-time payments. Showing the speed and any fee for each option lets recipients make the trade-off themselves.
Instant bank payouts and push-to-card both reach recipients in seconds. Bank payouts usually cost less as payouts grow, land directly in the bank account and keep card numbers out of your payout flow. Send over RTP or FedNow first, fall back to ACH where real-time rails don't reach, and keep push-to-card for recipients who prefer cards.
Pay recipients as fast as their bank allows. See how Aeropay Payouts sends US payouts over RTP and FedNow with ACH fallback.