How do fintech and trading apps fund accounts instantly?
Payments
November 18, 2026
|
Aeropay Team
This article was written by the payments nerds at Aeropay. Our goal is to provide you with solid insights to help your business operationalize more efficient, value-focused payments.
A new user signs up for a US trading app or neobank, links a bank account and deposits $500. A standard ACH debit takes days to settle. Until it does, the app has two options: make the user wait to trade, or credit the deposit early and absorb the loss if the payment comes back.
US fintech and trading apps fund accounts instantly in two ways. A guaranteed ACH debit lets the app credit the user as soon as the provider approves the deposit, because the provider carries the risk on eligible returns. A Request for Payment (RfP) delivers final funds in seconds, but only when the user's bank offers it.
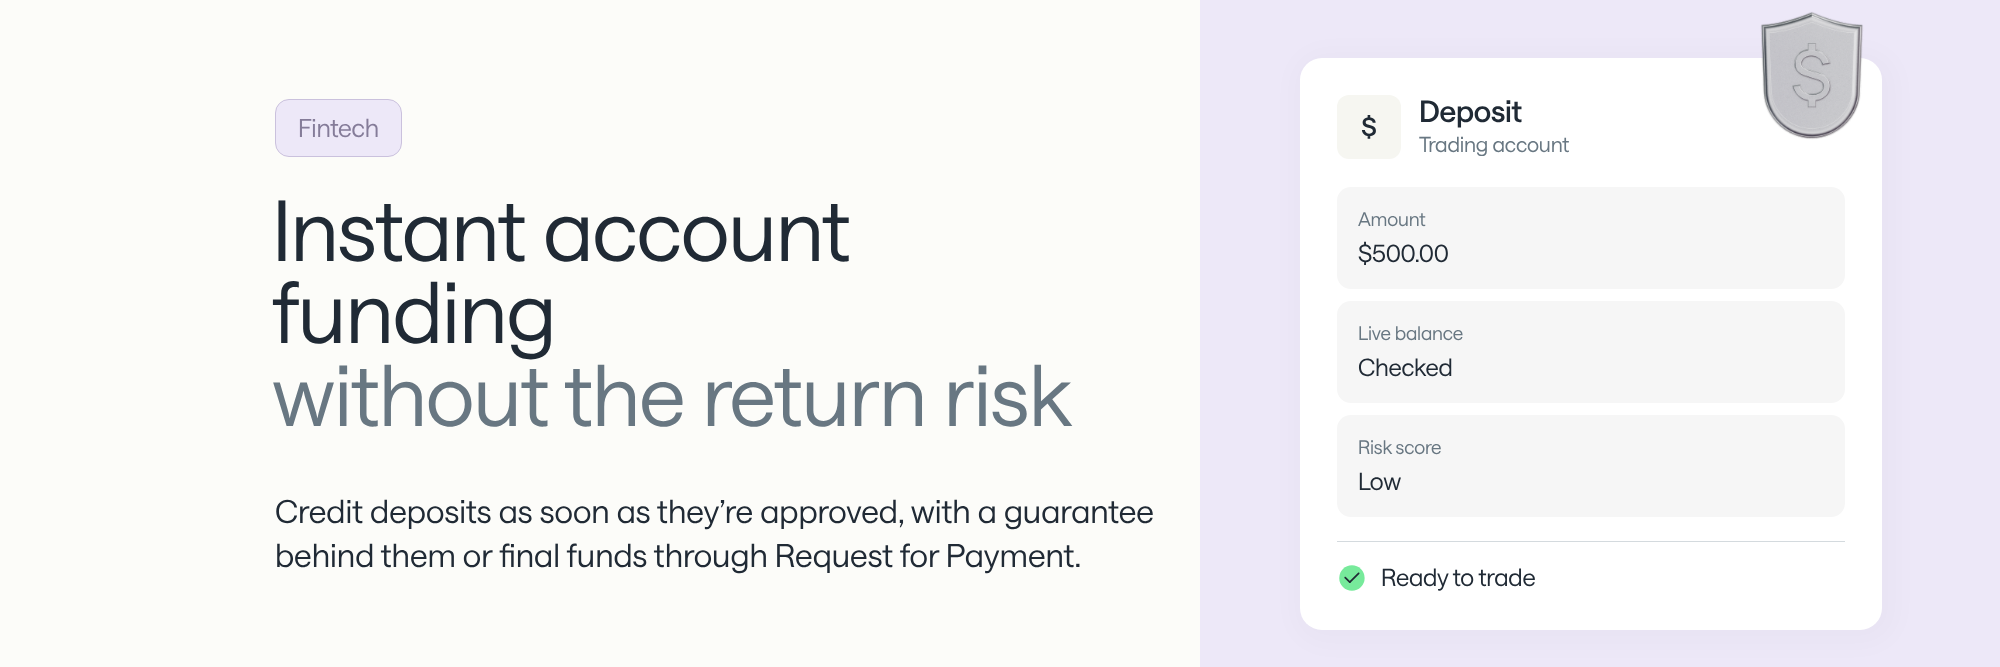
An instant deposit is credited only after four checks run in the seconds between the user tapping "deposit" and the balance updating.
If a check fails, the deposit should come back declined with a specific reason, or go through as a standard ACH debit with funds held until settlement.
An app that credits an unguaranteed ACH deposit immediately is betting the debit will clear, and on a trading app the exposure is bigger than the deposit. The user can buy a position that loses value or withdraw to another account before a return arrives, leaving the app to recover money from someone who may never repay it.
That window is long. Under the Nacha Operating Rules, a consumer's bank can return an unauthorized debit for up to 60 days after the settlement date. Fraudsters use this window: they fund an account with a debit they plan to dispute, trade or withdraw, then report the debit as unauthorized. We see the same pattern on gaming platforms, where a deposit can be spent seconds after it lands. Honest users cause returns too, through insufficient funds or a mistyped account number.
Returns also count against the app at the network level. Nacha sets a 0.5% threshold for unauthorized returns, and exceeding it is a rules violation. Nacha also sets return rate levels of 3.0% for administrative returns and 15.0% overall, and crossing either one triggers an inquiry.
Two methods let a user trade as soon as a deposit is approved without the app carrying the return risk: a guaranteed ACH debit and a Request for Payment.
Settlement and usable funds aren't the same thing. How fast do bank payments reach a business account? breaks down settlement timing by rail.
Request for Payment reaches only users whose banks offer it, and those banks are a subset of the banks on real-time rails. The RTP network reaches more than 74% of US demand deposit accounts through more than 1,200 participating financial institutions, according to Mastercard, and not every participant offers RfP. The Federal Reserve's FedNow service also supports request for payment, per the Richmond Fed.
Account funding was one of RfP's first approved uses. When The Clearing House expanded RfP on the RTP network in August 2023, its initial permitted use cases included transfers between accounts the same person owns, with brokers requesting money from a customer's bank account to enable immediate trading. The payer approves each request in their banking app, and the payee receives final funds in seconds.
Because RfP reach is partial, apps use it as an upgrade path: an RfP where the user's bank supports it, and a guaranteed ACH debit everywhere else.
The best payment providers for instant account funding approve each deposit against live bank data, stand behind the deposits they approve with a written guarantee, and pay withdrawals out as fast as deposits come in. Three questions separate them.
"Guaranteed" means different things at different providers. For example, Aeropay Guaranteed ACH covers eligible bank-initiated returns, across 50+ return types including insufficient funds, up to the merchant's agreed coverage limit. Ask every provider for its covered return types and coverage limit in writing, and ask whether any payment path sits outside the guarantee. What is guaranteed ACH? explains the mechanics.
A declined deposit should come back with a specific reason, such as low balance or a high risk score, so support can tell the user to try a smaller amount or another account. A generic decline sends the user to support and leaves the team guessing.
Users judge a trading app by how fast money comes back out. Aeropay routes payouts over RTP or FedNow first and falls back to ACH when the recipient's bank can't receive a real-time payment. Trading platform Topstep cut trader payout times from 3 days to 9 seconds with Aeropay instant payouts. What does a bank payment API need to handle both pay-ins and payouts? covers running both through one integration.
Debit card funding is fast, but card fees apply to every deposit and chargebacks stay possible. Many fintech apps keep debit cards as a backup for users who prefer them, and default to bank funding, where the provider can carry return risk on approved deposits.
Many providers move proven repeat depositors onto a faster, lower-cost path. Those deposits can sit outside the provider's guarantee, which leaves the return risk with the app. Before enabling a repeat-user path, ask which deposits it covers and who absorbs their returns.
When a guaranteed deposit is returned for a covered reason, the provider absorbs the loss up to the coverage limit, and the app keeps the funds it credited to the user. Returns outside the covered types or above the limit fall back to the app.
Fintech and trading apps fund accounts instantly by verifying the account, checking the live balance and scoring each deposit, then crediting approved deposits through a guaranteed ACH debit. Request for Payment adds final, in-seconds funds for users whose banks offer it.
See how Aeropay Guaranteed ACH lets your users trade as soon as their deposit is approved.