What's the cheapest way for an e-commerce store to accept bank payments?
Payments
November 4, 2026
|
Aeropay Team
This article was written by the payments nerds at Aeropay. Our goal is to provide you with solid insights to help your business operationalize more efficient, value-focused payments.
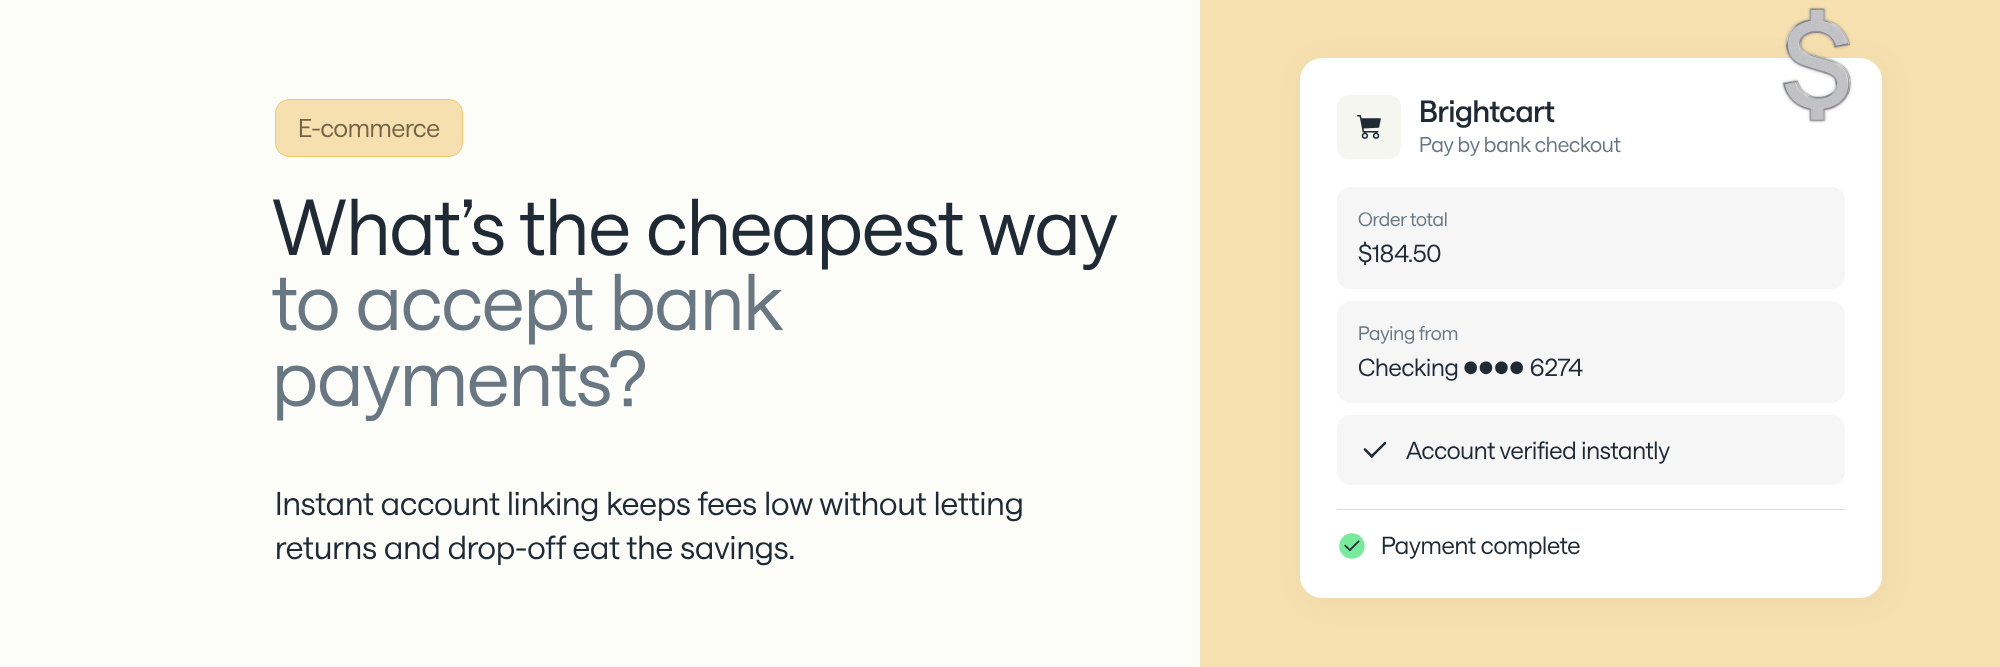
The cheapest way for a US e-commerce store to accept bank payments is pay by bank with instant account linking. The customer logs in to their bank at checkout, the account is verified on the spot, and the payment carries no card interchange. It beats typed-in ACH and micro-deposits on total cost because it cuts the returns and abandoned checkouts that erase a low fee.
An online card sale costs a US merchant about 2.31% plus $0.25 under interchange-plus pricing, based on Helcim's 2026 averages reported by The Motley Fool. A store that adds a bank payment option to avoid that fee still loses the savings if returned payments, abandoned checkouts, and manual reconciliation eat them. The cheapest option is the one with the lowest total cost.
For the head-to-head fee math against cards, see Pay by bank vs. credit cards: which costs merchants less? This guide compares bank payment methods against each other and shows how to set one up without giving the savings back.
A US online store has four realistic ways to take money directly from a customer's bank account.
| Option | How it works | Where the cost hides | Customer experience | Best for |
|---|---|---|---|---|
| Manual bank transfer or wire instructions | You show your account details; the customer sends the money from their bank | Staff time matching payments to orders, delayed shipping, wire fees paid by the customer | Poor. The customer leaves your site and comes back | Rare, high-value B2B orders |
| ACH with typed-in account details | The customer enters routing and account numbers; you debit by ACH | Typos, wrong accounts, insufficient funds, and unauthorized returns that arrive after you've shipped | Clunky. The customer has to find and type their routing and account numbers | Low-risk repeat customers, invoices |
| ACH with micro-deposit verification | Two small test deposits confirm the account before the first debit | Lost sales while customers wait for the test deposits to post and then forget to confirm | Slow. The first purchase can't complete at checkout | Subscriptions where the first charge can wait |
| Pay by bank with instant account linking | The customer logs in with their bank at checkout; the account is verified and the payment initiated in one step | The provider fee, plus any return risk the provider doesn't cover | Fast. Similar to a card checkout | Most online stores, especially higher-ticket or repeat purchases |
A fifth option, Request for Payment on the RTP network, lets a store ask the customer to push an instant payment from their bank. It removes return risk because the payment is final, but support depends on whether the customer's bank offers it, according to The Clearing House. For how it works, see Request for Payment (RfP): How to enable instant pay-ins.
The total cost of acceptance has six parts, and the processing fee is only one of them.
A method with a low fee and high returns costs more than one with a slightly higher fee and almost no returns, which makes “cheapest” a total-cost question.
Four decisions set the total cost of bank payments.
Ask each provider these eight questions before you sign.
How to choose a pay by bank provider in the US goes deeper on provider evaluation.
Yes, on the processing fee. An online card sale costs a US merchant about 2.31% plus $0.25, and a bank payment carries no card interchange. The total cost stays lower when the store verifies accounts at checkout and its provider covers returned payments.
A manual bank transfer avoids a processor fee. It moves the cost to staff time spent matching payments to orders, slower fulfillment, and sales lost when customers leave the site to send the money.
Not with instant bank linking. The customer logs in with their own bank, the bank issues a secure token, and the store never sees their password.
The cheapest way for a US e-commerce store to accept bank payments is pay by bank with instant account verification, because it keeps fees low without letting returns and checkout drop-off eat the savings. Judge every option on total cost of acceptance, and ask who carries the return before you compare fees.